
 11 hours ago
6
Micron released its fiscal Q4 2026 financial results on Wednesday, expectedly setting another record for revenue with $54.23 billion for the quarter, up nearly five times since the same period last year. Micron also hit a record 87% gross margin, the largest contributor to which was Micron's Mobile and Client (consumer) business unit. Further, Micron's client business was the only one that shipped less memory last quarter, despite bringing in the highest operating margin at 88%.
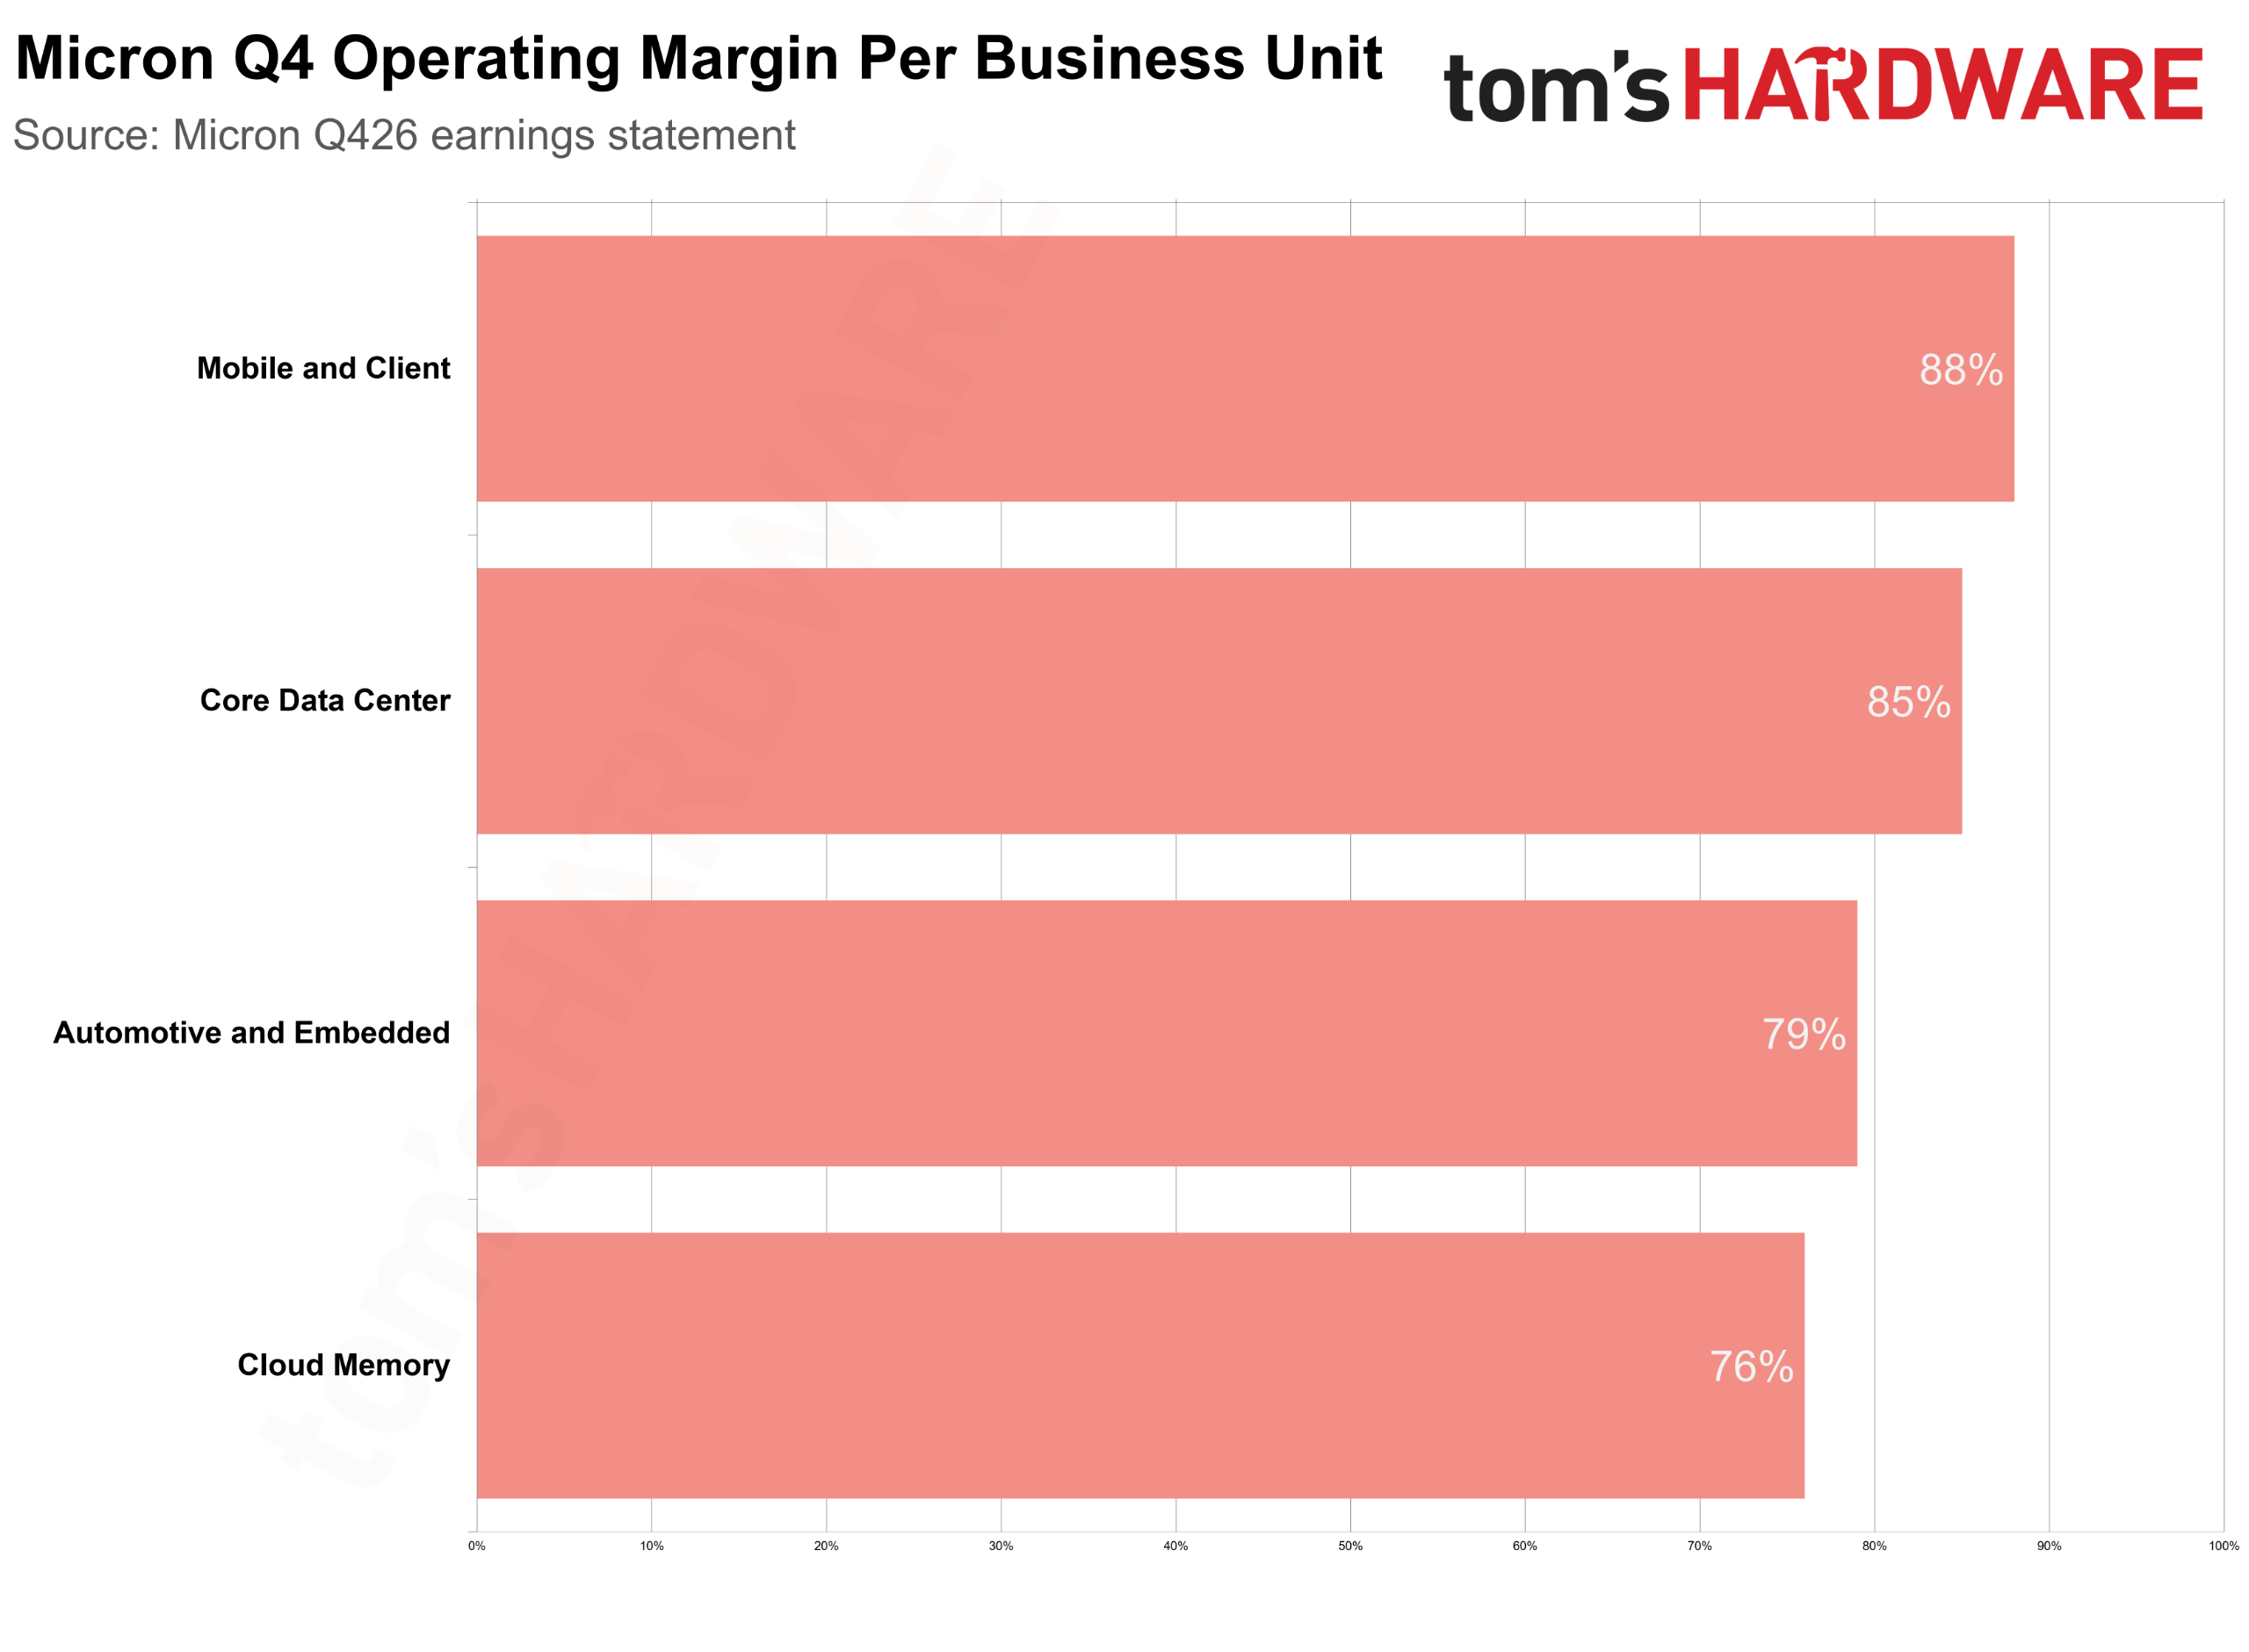
Micron's margins overall are up significantly year-over-year; Core Data Center surged from 25% to 85%, and Automotive and Embedded have climbed from 20% to 79%. The Mobile and Client unit also saw significant growth, with a 29% operating margin in fiscal Q4 2025, and now a margin of 88%. Cloud Memory margins grew, though not to the same extent as other units, moving from 48% to 76%.
The gross margins are interesting to look at, too. In a financial statement, the gross margin equals revenue minus cost of goods. Operating margin, on the other hand, equals revenue minus cost of goods and all other operational expenses. The operating margin simply excludes taxes and interest.
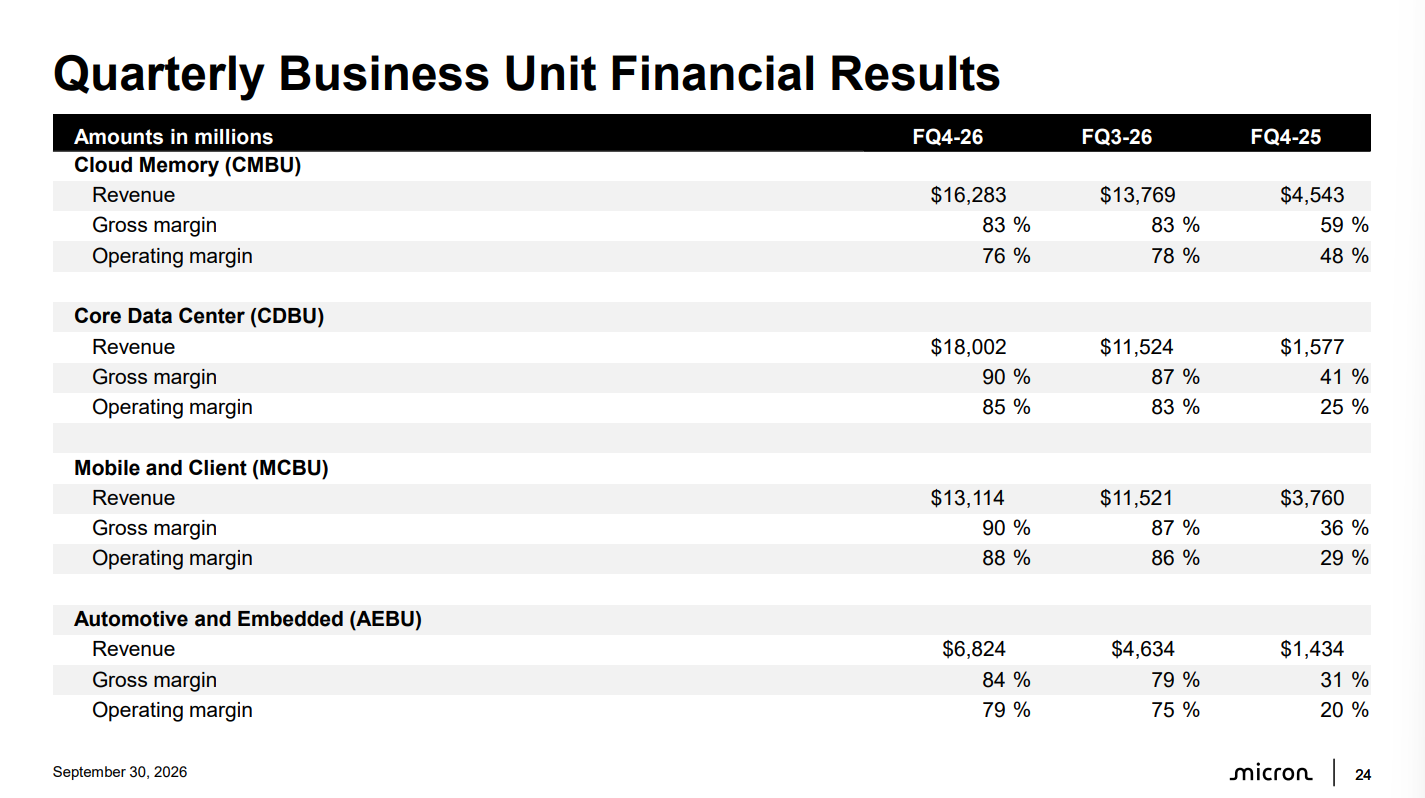
The gap between gross and operating margin is what's interesting in the breakdown above. The Mobile and Client unit has the smallest gap, with only a 2% difference. The Core Data Center unit matches the Mobile and Client unit with a 90% gross margin, but it has a lower operating margin at 85%. In other words, the cost of running Micron's consumer business is extremely low relative to the amount of revenue it currently generates.
It also saw the lowest amount of growth for the quarter, with revenue up 14% quarter-over-quarter. Micron says this was "driven by higher pricing, partially offset by lower bit shipments." Out of Micron's four business units, the Mobile and Client unit was the only one that shipped less memory in the past quarter.
For clarity's sake, a bit shipment is just a shipment. Micron measures shipments in bits rather than units. It's the capacity Micron has shipped in a quarter, not the actual number of DRAM or NAND chips.
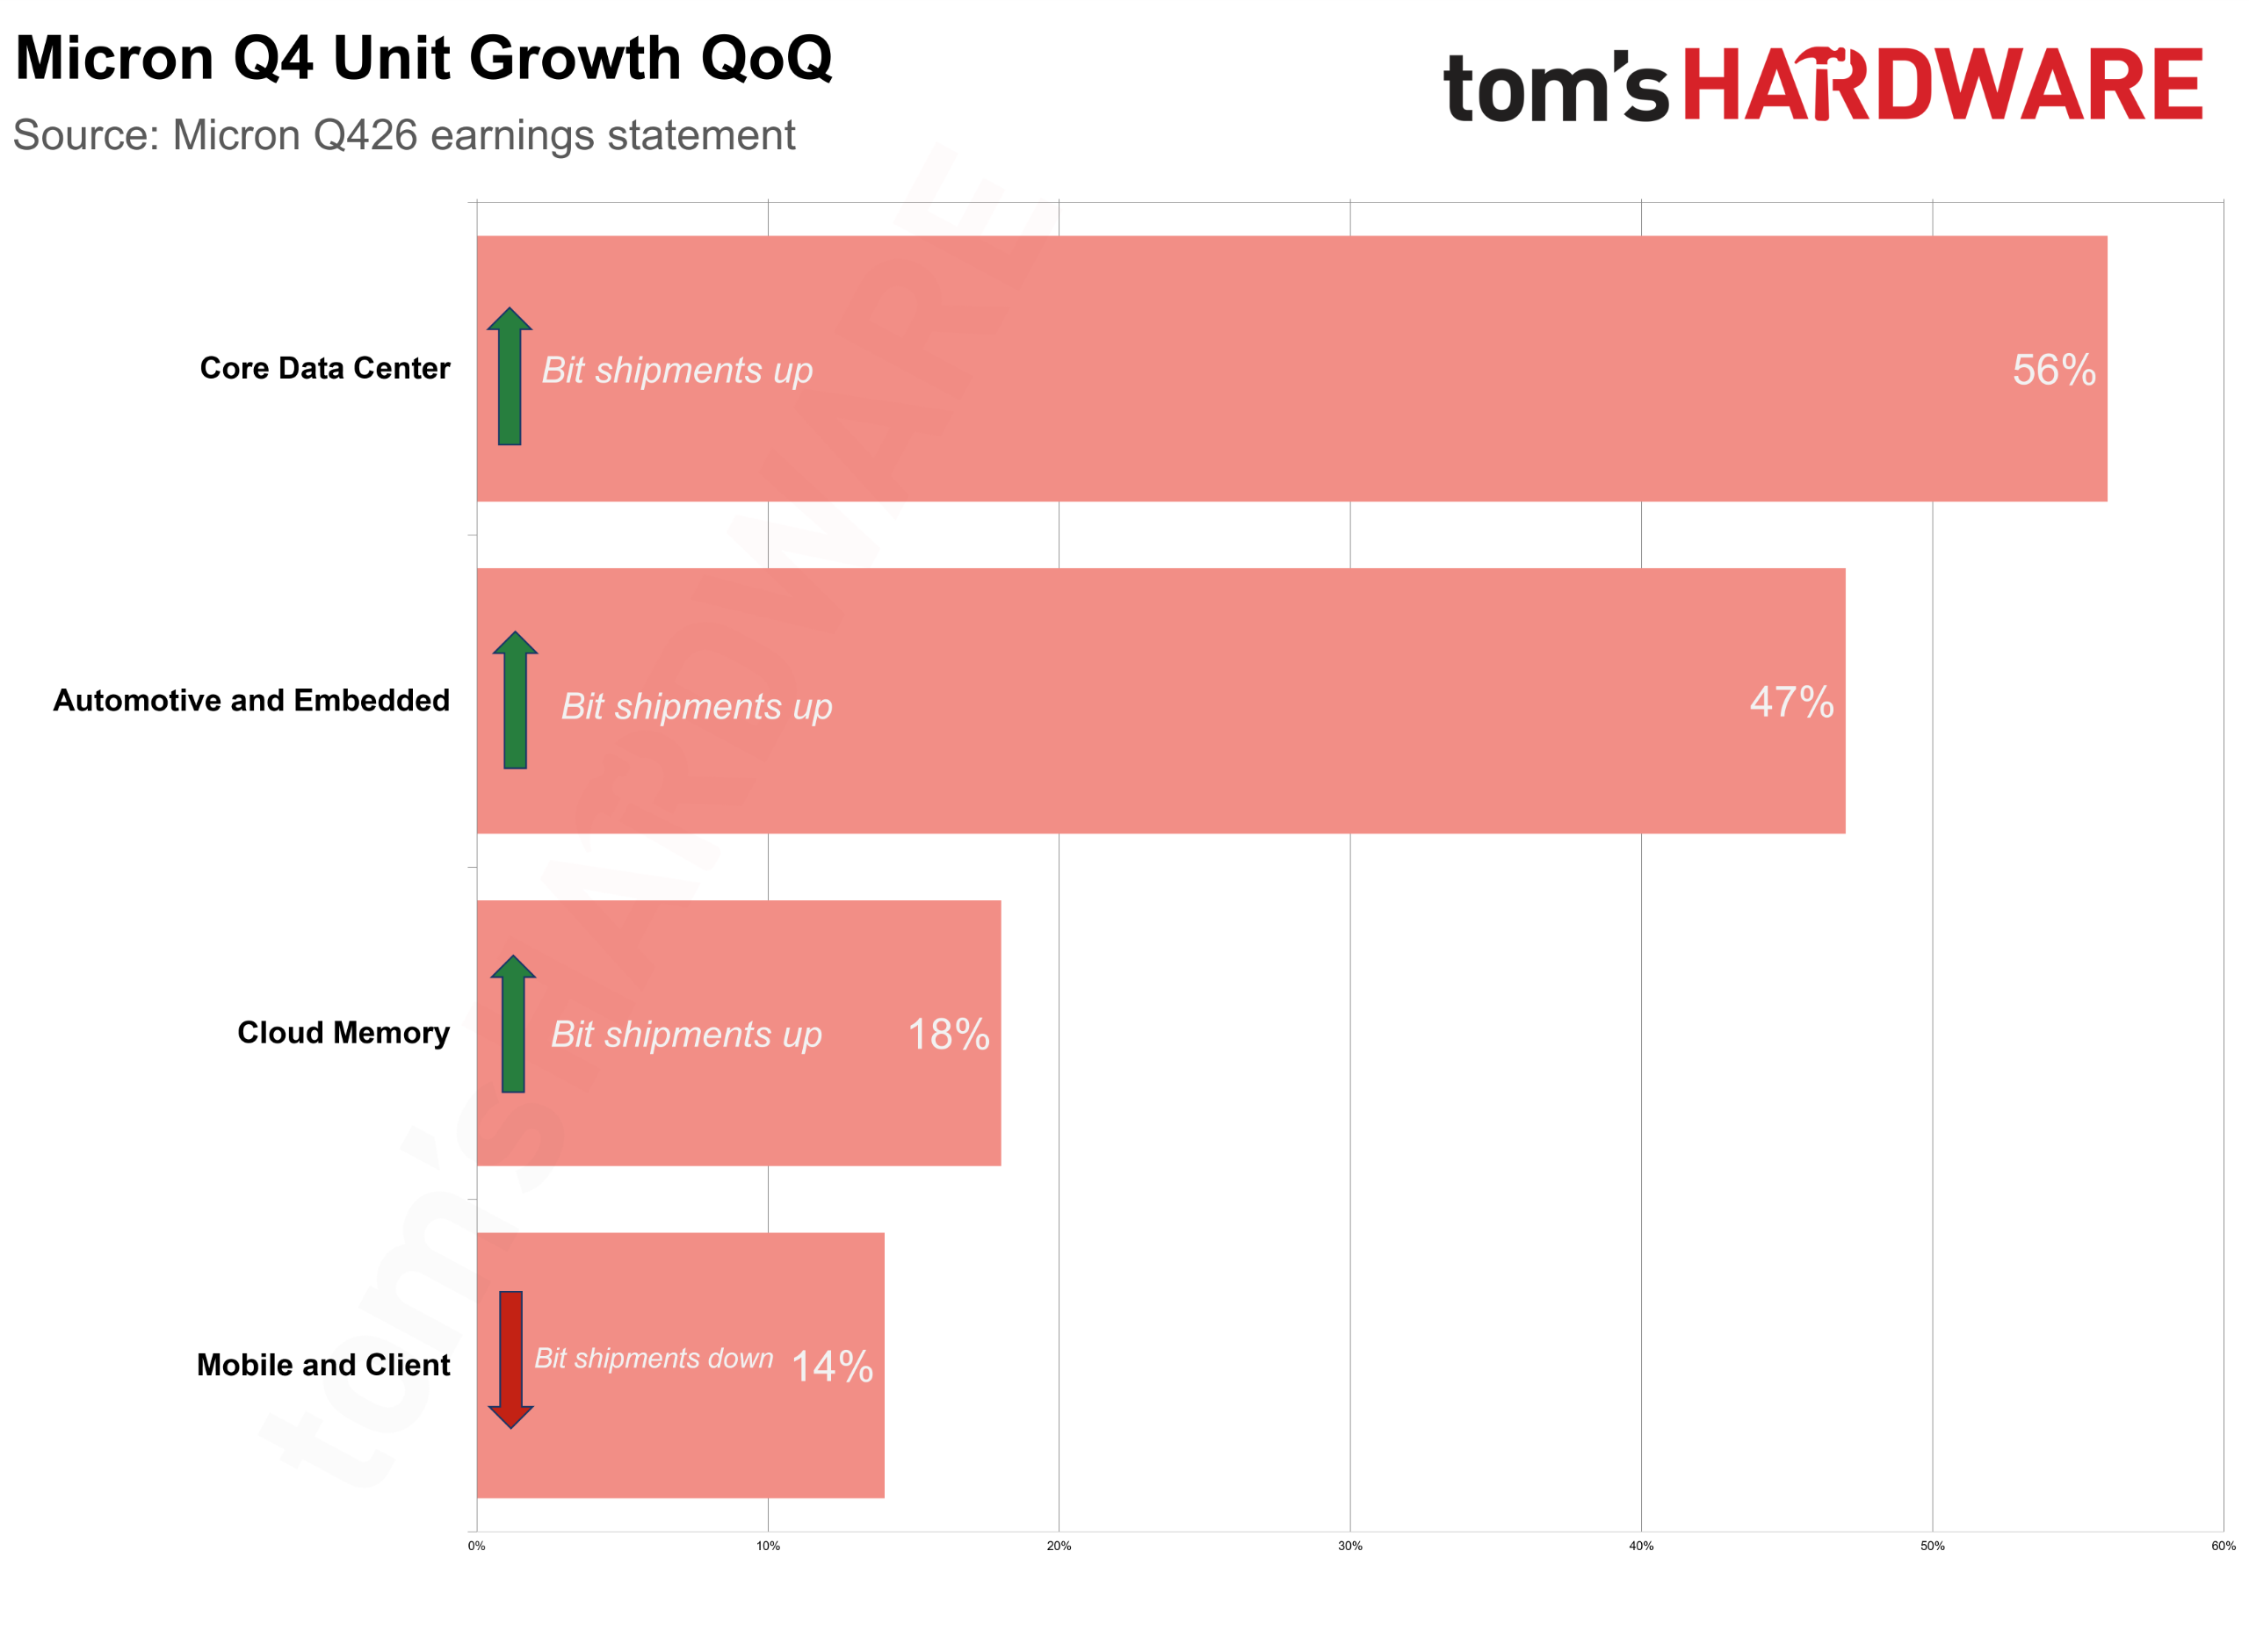
Outside of Mobile and Client, Micron attributes higher revenue to higher pricing and bit shipments. The situation in the Mobile and Client unit echoes a sentiment we've heard elsewhere: growth in the consumer market is still happening, but it's driven by higher pricing, not growth in shipments.
Get Tom's Hardware's best news and in-depth reviews, straight to your inbox.
Earlier this year, Intel's David Zinsner, chief financial officer, attributed a 13% YoY growth in Intel's consumer business to higher average selling price (ASP), not increased unit sales. Zinsner clarified that Intel "thought we had seen some inflation on our cost and needed to pass that on to the end customer."
Micron's outlook for fiscal Q1 2027 has revenue set at another record of $61.5 billion ± $1.5 billion, with gross margin rounding from 87% in fiscal Q4 2026 to 86.25%.
Image 1 of 2
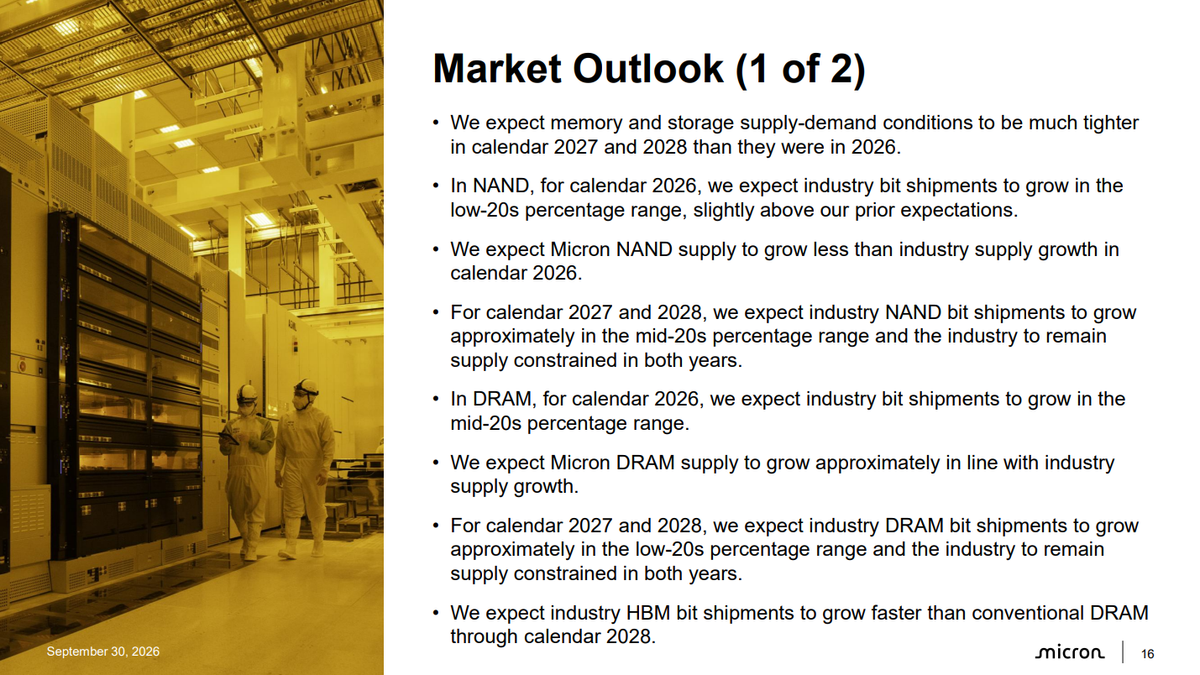
Another record quarter signals more squeeze on the DRAM and NAND markets. Echoing rival SK hynix, Micron says it expects memory and storage to be "much tighter" in 2027 and 2028, claiming that the company expects the industry to be supply-constrained in both years. That's despite a growth in supply that Micron anticipates.
The company says it expects industry NAND bit shipments to grow in the mid-20% range, and DRAM bit shipments to grow in the low-20% range. The industry broadly will produce more memory over the next two years, says Micron, but that still won't keep pace with demand.
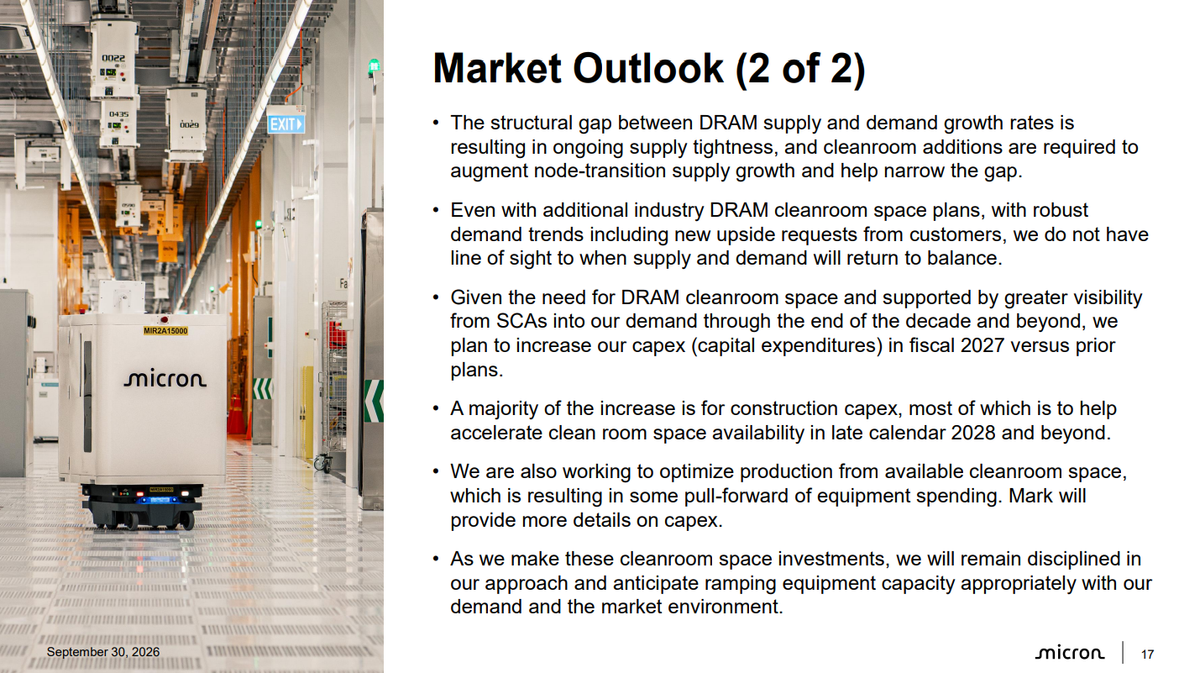
Worrying still is this line in Micron's earnings slides: "we do not have line of sight to when supply and demand will return to balance." However, the company says it plans to increase its capital expenditure (capex) in fiscal 2027 compared to its prior estimates.
A "majority" of that increase is set aside for construction of additional clean room space, which Micron has set for 2028 through the end of the decade. Hopefully, that additional clean room space coming online will ease supply constraints, but we're still a long way from that point.
Follow Tom's Hardware on Google News, or add us as a preferred source, to get our latest news, analysis, & reviews in your feeds.



 English (US) ·