 2 hours ago
10
Key Highlights
- UBS elevated UK equities to “attractive” status following recent market correction
- The Swiss bank increased its UK corporate earnings growth projection to 16% for 2026, revised upward from 11%
- New FTSE 100 price targets established at 11,200 by December 2026 and 11,500 by June 2027
- Barclays identifies FTSE 250 companies trading at approximately 20% below fair value on price-to-book metrics
- BlackRock characterizes UK market as an “exceptionally compelling diversifier” with promising prospects in banking and mining sectors
Leading investment banks UBS and Barclays are highlighting British equities as a compelling buying opportunity following recent market weakness. The combination of depressed valuations, strengthening corporate earnings, and beneficial commodity sector exposure is creating favorable conditions for UK-listed companies.
UBS Elevates Earnings Projections and Establishes Bullish FTSE 100 Price Targets
UBS has upgraded its perspective on British equities to “attractive” after observing recent price declines. The Swiss banking giant increased its 2026 earnings growth projection for UK corporations to 16%, representing a significant revision from its previous 11% forecast. The primary catalyst for this upward adjustment stems from elevated energy commodity prices.
The investment bank has established a FTSE 100 price objective of 11,200 by December 2026. Additionally, UBS projects the index will reach 11,500 by June 2027, marking a substantial increase from the 10,650 level recorded on September 15, 2026.
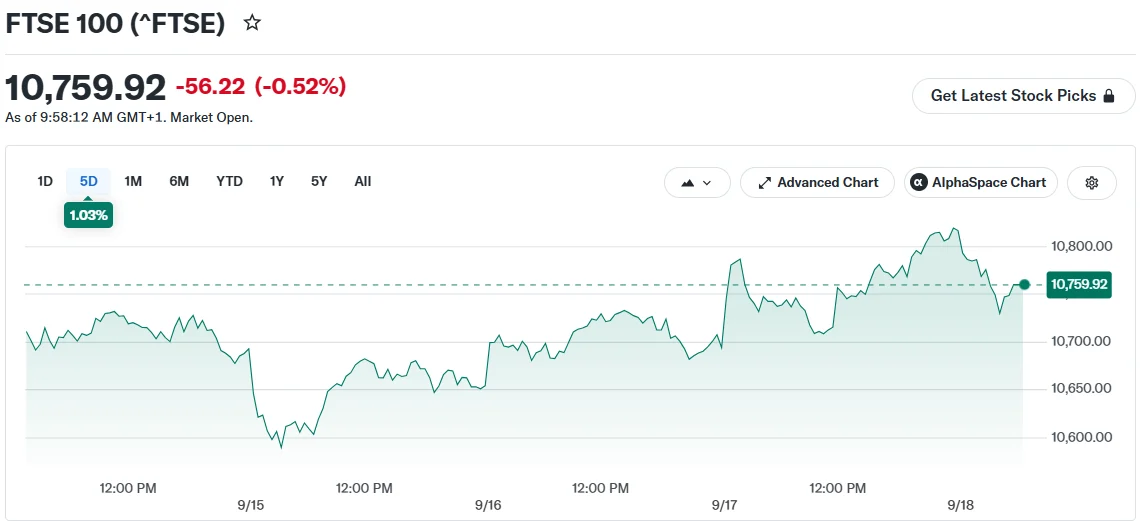 FTSE 100 (^FTSE)
British stocks currently exhibit a forward price-to-earnings multiple of 12.4 times earnings. This valuation sits modestly below the long-term median of 12.8 times observed since 1990.
Energy-exposed companies are projected to contribute approximately 18% of MSCI UK index earnings during the current year. UBS analysts noted that risks to their earnings forecasts tilt toward the upside, given potential further appreciation in energy commodity prices.
Notwithstanding this upgrade, UBS continues to rank UK equities as “Least Preferred” when compared against other international markets. The bank anticipates earnings growth will decelerate to roughly 9% in 2027 as commodity tailwinds diminish.
UBS maintains a preference for Eurozone equities over British stocks on a relative basis. The bank expresses sector-level conviction in European technology, industrials, banking, consumer discretionary and healthcare companies.
Barclays and BlackRock Identify Compelling Value in British Equities
Barclays characterized UK equities as “unloved but not a bad place to hide,” suggesting that current market concerns surrounding artificial intelligence and petroleum could paradoxically benefit the FTSE 100.
The British bank emphasized that FTSE 250 constituents are currently changing hands at approximately a 20% discount on price-to-book valuation metrics. Barclays noted this discount persists despite corporate profitability metrics that remain robust relative to international counterparts.
The bank’s highest-conviction UK equity recommendations with maximum upside potential include Rentokil, Trustpilot and Shawbrook. Barclays expresses sector preference for British industrials, financials, utilities, property companies and selective consumer-facing businesses.
BlackRock’s Helen Jewell described the UK market as “a really interesting diversifier,” highlighting dividend-generating sectors, banking institutions and commodity mining companies as particularly attractive opportunities.
Jewell’s investment team maintains an overweight position in mining companies driven by elevated copper pricing. She additionally observed that certain UK stocks negatively impacted by the “AI loser” trading narrative continue to offer compelling value based on fundamental analysis.
Potential Downside Scenarios Warrant Consideration
UBS outlined a bearish scenario whereby the FTSE 100 could decline to 7,700 by June 2027. Key risk factors include energy supply disruptions emanating from Middle Eastern conflicts, resurgence of protectionist trade policies, commodity price deterioration, and sharply elevated government bond yields.
Elevated interest rate environments represent a near-term headwind for UK equity valuations, according to UBS analysis. However, the bank maintains confidence that strengthening corporate earnings can sufficiently compensate for higher discount rates.
Britain additionally confronts a challenging domestic economic environment. Obstacles include an ongoing cost-of-living squeeze, accelerating inflation pressures, and the highest government borrowing costs among G7 nations.
The newly elected UK government is scheduled to unveil its inaugural budget next month. Policymakers face the delicate task of maintaining fiscal credibility while accommodating increased defense expenditures and household financial support programs.
The post Major Banks Flag UK Equities as Undervalued Investment Opportunity appeared first on Blockonomi.




 English (US) ·